How to Manage Your Monthly Salary in India: Budget & Plan
Managing your monthly salary well isn't about strict deprivation—it's about giving your money clear jobs so everyday expenses, unexpected bills, and future milestones don't create constant stress. For women in India navigating career breaks, changing roles, and longer life spans, a simple, repeatable salary plan brings real calm and confidence.
1. Budget Your Salary With the 50:30:20 Rule
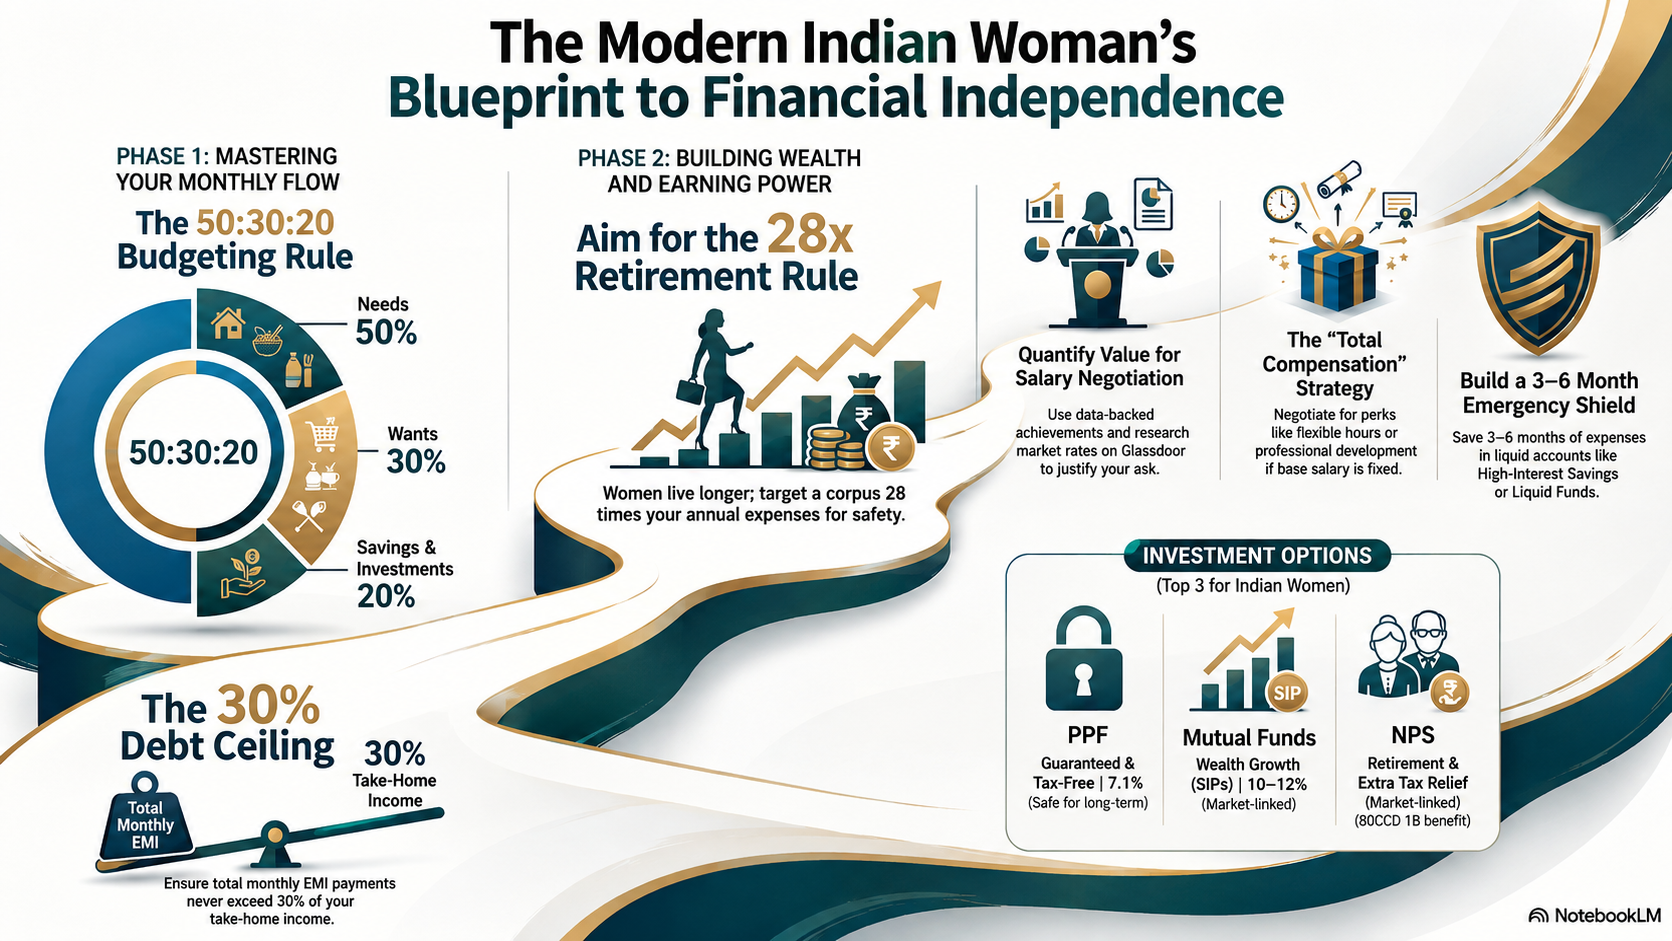
A clear budget helps you see where your pay goes before the month runs away from you. Many people find the 50:30:20 framework easy to adapt to their take-home pay:
- 50% for Needs: Essential living costs such as rent, groceries, utility bills, insurance premiums, and minimum loan EMIs.
- 30% for Wants: Flexible lifestyle spending like dining out, shopping, hobbies, and outings.
- 20% for Savings & Goals: Consistent contributions toward emergency savings, medium-term goals, and long-term plans.
Setting up an automatic transfer on payday—rather than waiting to see what remains at month-end—makes consistency easier. Keeping total monthly EMIs comfortably below your take-home pay also protects your cash flow from feeling squeezed.
2. Build an Emergency Buffer Before Locking Money Away
An emergency fund is your first line of defense when a medical bill, family need, or job transition happens unexpectedly. Aim to build a dedicated reserve covering several months of essential expenses (and a larger buffer if you freelance or anticipate a career break).
Keep emergency money accessible and low-volatility—such as in a high-interest savings account, short-term deposit, or liquid fund—rather than tying it up in long-lock-in schemes or high-volatility assets you might have to sell at an awkward time.
3. Plan Ahead for Career Breaks and Longer Horizons
Career pauses for caregiving, relocation, or upskilling are common, and women often plan across a longer post-work horizon. Planning ahead reduces panic when income changes:
- Keep long-term retirement accounts like EPF or PPF active rather than cashing them out impulsively during a break when continuity matters.
- Adjust monthly contributions realistically during leaner stretches so you stay in the habit without straining monthly essentials.
- Review health and term insurance protection so one medical event doesn't wipe out years of disciplined saving.
4. Understand Core Options Without Chasing Hype
Once your basics and emergency buffer are in place, learn how common instruments work—such as PPF, mutual funds via SIPs, NPS, and tax-saving provisions—before committing money. Focus on clarity, liquidity, time horizon, and risk rather than hot tips or guaranteed shortcuts. If you want personalized investment advice, tax filing, or product recommendations, speak with a SEBI-registered adviser, CA, or licensed professional.
5. Advocate for Fair Pay and Know Key Protections
Managing salary isn't only about cutting expenses—it also includes understanding your total compensation (base pay, bonuses, benefits, and flexibility) and preparing clearly when negotiating pay or career moves. Staying informed about basic financial and legal protections—such as nominations, joint/individual account clarity, and property/inheritance rules like the Hindu Succession (Amendment) Act, 2005—supports long-term peace of mind.
Want structured frameworks and checklists to put these salary habits into practice? Explore WENA Programs, browse practical tools in the WENA Store, or connect with vetted specialists via WENA Implementation Partners.